Edinburgh sits a long way from Hong Kong, but the two cities share more commercial history than might first appear. Scotland developed a sophisticated banking tradition early, and Scots carried that experience into the trading world of the nineteenth century. When HSBC opened in Hong Kong in 1865, its founder was Thomas Sutherland, a Scottish shipping executive who saw the need for a local bank to finance the rapidly expanding trade between Europe and Asia. Shipping, trade and finance were intertwined from the beginning.
There was another Scottish connection to the China trade that was more tangible. Jardine Matheson grew out of Scottish merchants operating between Britain and Asia. Sir Alexander Matheson, a China merchant and nephew of Jardine Matheson cofounder James Matheson, returned to Scotland and acquired the Ardross estate in the Highlands in 1845. Ardross Castle is now familiar to millions as the setting for the BBC’s The Traitors. It is also a place I know well because I grew up in Ardross and worked in the castle grounds during my school summer holidays.
You would be forgiven for thinking this is an unusually broad place to begin an article about an Oslo listed E&P company. But BW Energy, which I will refer to as BWE, sits at the intersection of shipping, offshore oil, banking and international finance, with relationships stretching between Europe and Asia. The financial instruments are modern, but the commercial habits behind them are much older. Shipping is an international financing business almost as much as it is an operating business. A vessel may be built in one country, owned through a company incorporated in another, financed by banks elsewhere and chartered to customers around the world. The skill lies partly in operating it, but also in deciding who should own it, how it should be financed and how much risk should remain with the equity.
The BW story began in British ruled Hong Kong in 1955, when Yue Kong Pao founded World Wide Shipping. Pao had worked in banking in Shanghai before moving to Hong Kong in 1948. He entered shipping with a single vessel and built World Wide into one of the largest privately controlled shipping businesses in the world. Leadership later passed to Helmut Sohmen, Pao’s son in law, and the family continued expanding across international shipping.
From ships to oil fields
In 2003 World Wide acquired Bergesen, one of Norway’s great shipping companies and then the world’s largest operator of LNG and LPG carriers. Bergesen already had an offshore business, which became the foundation of BW Offshore. By then floating production, storage and offloading technology (FPSO) had become an important part of offshore oil development. An FPSO could receive production from offshore wells, process it, store the crude and transfer it directly to tankers. For an oil company, it was a production facility. For a shipping company, much of the asset was familiar. At heart, an FPSO is still a ship. It can be bought, converted, financed, leased and sometimes moved to another field.
A conventional E&P may look at an offshore development and see one large investment programme. A shipping business is accustomed to asking which assets need to be owned, which can be leased, what debt each can support and when the cash obligations should fall. BW Offshore accumulated decades of experience owning FPSOs, converting them, financing them and moving them between fields. Eventually that raised another possibility: instead of earning a contractual return from supplying the vessel, BW could own part of the oil field and participate directly in the value created by bringing it into production.
Dussafu proved the model
The decisive move came offshore Gabon. In 2016 BW Offshore and BW Group created BWE to pursue upstream opportunities and acquired an operating interest in the Dussafu licence. Panoro Energy was already a partner and brought continuity from the earlier exploration and appraisal work.
Dussafu showed that BWE could do considerably more than provide infrastructure. It could operate an upstream business, drill wells, develop discoveries and take responsibility for turning a resource into a producing field. An existing very large crude carrier was converted into the BW Adolo FPSO, investment was phased and first oil was achieved in September 2018, 18 months after the initial investment and within budget and schedule. BWE later said its approach reduced upfront development spending and FPSO commitments by around 60 per cent compared with the previous plan.
Further discoveries and development have since turned Dussafu into a broader production hub, producing 24,400 barrels a day net to BWE in 2025. BWE then moved into Brazil in a more modest way, acquiring the producing Golfinho field from Petrobras in 2023. Golfinho contributed another 5,500 barrels a day in 2025, taking group production to just under 30,000 barrels a day.
With Dussafu and Golfinho as its producing assets, BWE reported $798 million of revenue, $414 million of EBITDA and $315 million of operating cash flow in 2025. In the first half of 2026 it generated another $252 million of EBITDA and $222 million of operating cash flow. There is a lot to like about the business BWE has built. It has combined offshore operating experience, existing infrastructure and disciplined development to create a profitable producing base. There are further opportunities around Dussafu and Golfinho, while the company is also pursuing opportunities in Angola. At the beginning of September the equity market valued BWE at around $1.5 billion, with an enterprise value of approximately $2.5 billion. It is a meaningful mid cap E&P with real operating capability and several possible routes for growth.
That record makes the decision to commit so much financial and management capacity to Maromba particularly important, because Maromba is a very different proposition from the developments on which BWE built its reputation.
Maromba changes the risk
The Maromba Field lies in the southern Campos Basin offshore Brazil. It was discovered in 1980 and is not a frontier exploration story, but neither does it appear to be a simple development. Nine exploration and appraisal wells were drilled and oil was found in eight of them across several reservoirs. That is a substantial amount of subsurface information for a field that nevertheless remained undeveloped.
Maromba was declared commercial in 2006. Chevron later considered a pilot production system and at one point envisaged first oil in 2013, yet the development concept was still being evaluated years later. Petrobras subsequently worked on its own development plan, but that was not sanctioned either, and Petrobras and Chevron eventually put their interests up for sale. The history does not show that Maromba is a poor resource. Both previous owners and BWE have regarded the main reservoir as extensively appraised. What the history does show is that establishing the presence of oil and finding a sufficiently attractive way to develop it are very different things.
BWE acquired Maromba in 2019 for $115 million and initially expected to move much faster. Its early plan targeted first oil by the end of 2022. The pandemic interrupted that timetable and BWE deliberately slowed investment during the oil market collapse, but that does not explain the full period between acquisition and sanction. The company continued working on the reservoir and changed the development plan. By 2022 it was proposing a phased subsea project using an existing FPSO, initially with three production wells and another three to follow, with first oil moved to 2025.
That was not the project ultimately sanctioned. BWE continued reworking Maromba and eventually moved to a materially different design using a converted jack up rig as a permanent drilling and wellhead platform alongside a refurbished FPSO. Final investment decision came in May 2025, almost six years after BWE acquired the field and 45 years after discovery.
BWE has a credible answer to anyone interpreting that history as evidence of high geological risk. When an investor asked management directly about Maromba’s subsurface risk on the second quarter 2026 results call, Chief Operating Officer Brice Morlot pointed to the years spent working with the data and the amount of drill stem test information available. Management said it was confident in the geology and saw little risk to the production forecast coming from the subsurface.
That answer deserves weight. BWE is not inexperienced in subsurface work either. Dussafu has given it genuine experience of exploration, appraisal, reservoir modelling and development drilling. Its institutional history as an E&P operator is nevertheless short compared with its much deeper experience in offshore infrastructure, engineering and finance. Maromba therefore asks a relatively young upstream organisation to place considerable weight on its reservoir judgement in a heavy oil field studied for decades by Petrobras and Chevron and taken through several development concepts before BWE arrived.
The concern is not whether there is oil at Maromba. The main reservoir is highly delineated and management has expressed considerable confidence in its understanding of it. The concern is the combination of a difficult development history, heavy oil, a relatively young institutional subsurface capability, the size of the project and the consequences for BWE if production develops materially differently from the current plan.
The development targets around 122 million barrels of proved plus probable reserves. BWE expects to spend approximately $1 billion before first oil, another $200 million completing the initial six well campaign and a further $300 million on a second six well campaign. First oil is targeted by the end of 2027 and plateau production is expected to reach 60,000 barrels a day.
The economics are attractive if BWE delivers the plan. Management estimates an internal rate of return above 30 per cent at $60 Brent, a breakeven around $40 Brent on a 10 per cent return basis and production costs below $10 a barrel during the first five years. Maromba also sits under one of Brazil’s original Round Zero concessions rather than a production sharing contract and BWE expects royalties to be reduced to 5 per cent before first oil. Brazil can impose additional special participation payments on sufficiently profitable concession fields, but shareholders should still retain meaningful exposure to higher oil prices.
Management is understandably confident. BWE has described Maromba as ranking among the strongest projects globally on its economics and says execution remains on time and on budget. A resource that has remained undeveloped for decades could become a highly profitable 60,000 barrel a day field and transform the company’s cash generation.
The size of the commitment is nevertheless difficult to ignore. BWE produced just under 30,000 barrels a day in 2025, while Maromba alone is expected to reach 60,000 barrels a day, roughly twice BWE’s entire 2025 production. The total $1.5 billion investment is approximately equal to the current market value of all BWE’s equity. PetroEquity Signal has looked repeatedly at what can happen when offshore developments become too large relative to the companies carrying them. Tullow and Kosmos provide different examples. An asset does not need to fail for the equity to suffer. It only needs to cost more, arrive later or generate less cash than the financial structure around it can comfortably absorb.
This is not a concern invented solely for this article. BWE’s annual report identifies cost, schedule, contractor, supply chain, regulatory and technical risks around major developments. An analyst also challenged management directly on Maromba execution risk during the first quarter 2026 results and asked how a delay would affect the capital programme. Chief Executive Carl Arnet said BWE had tested a six month delay and could sustain it comfortably, but that beyond six months the position would become tighter, depending on factors including the oil price. Management has therefore created meaningful room for error without claiming that the room is unlimited.
The financing arrangements are impressive but the risk remains significant
BWE’s response to the size of Maromba reflects its shipping heritage. It did not reach final investment decision in May 2025 with every part of the financing already completed. At sanction it expected to use cash from the existing business alongside several forms of external finance, while BW Group committed a $250 million shareholder facility to provide additional support.
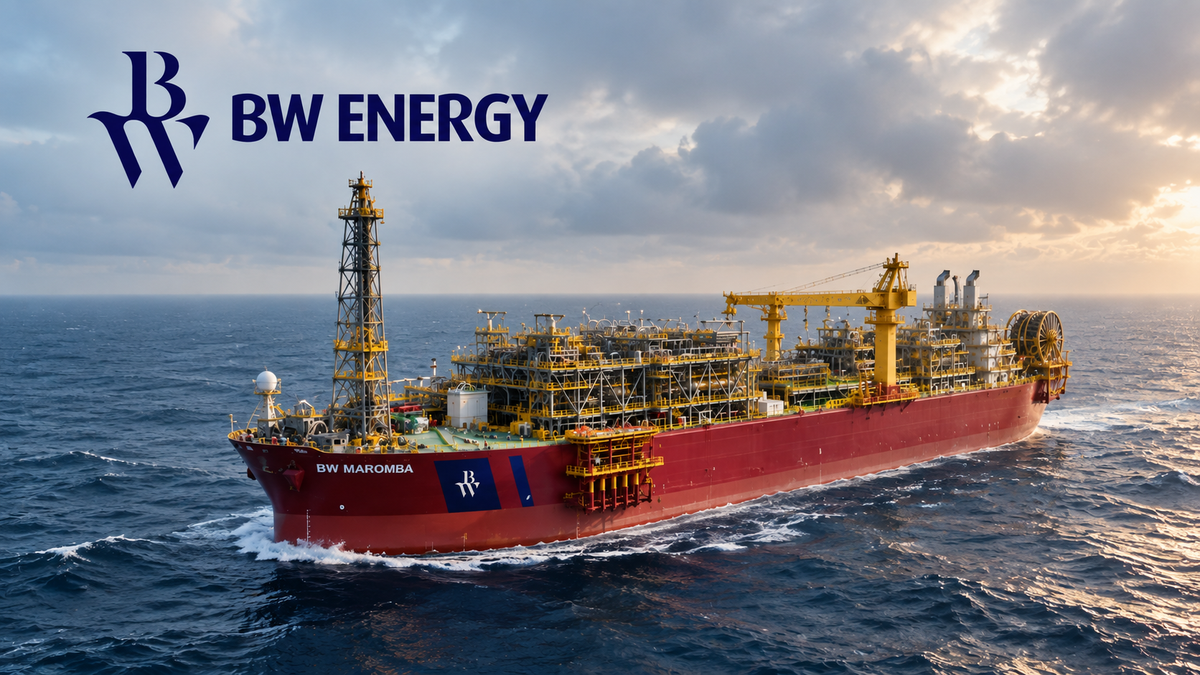
The largest project facilities followed. BWE acquired the Maromba FPSO from BW Offshore for $50 million and is having it refurbished at the COSCO yard in China. A $365 million project finance facility covers around 80 per cent of the FPSO cost. Sinosure supports the financing, China Exim is among the lenders and several Middle Eastern banks participate.
The wellhead platform has been financed separately. Minsheng Financial Leasing is providing $274 million for the purchase of the jack up rig and its conversion, with much of the payment burden falling after Maromba is expected to start producing. BWE also has borrowing supported by Dussafu, operating cash from its existing fields and a separate $250 million corporate revolving facility from DNB, backed by BW Group. Part of production has been hedged during the heavy investment period and BWE reported $544 million of available liquidity at the end of June 2026.
There is real financial skill in this structure. A more conventional approach could leave a mid cap trying to fund much of a $1.5 billion offshore development from operating cash, corporate debt and perhaps new equity. BWE has instead divided the problem. The FPSO supports one financing package, the platform another, producing reserves support additional borrowing and corporate facilities provide liquidity.
Maromba’s financing also brings the story back to Asia. COSCO is refurbishing the FPSO, Sinosure supports its financing, China Exim provides capital and Minsheng is financing the platform. Minsheng has also financed assets used by BWE in Gabon. Many independent E&Ps can access bank debt, bonds and reserve based lending. Fewer have longstanding relationships across shipyards, export credit agencies and maritime leasing companies, and this wider network appears to give BWE financing options that many companies of comparable size would not have.
The structure materially reduces the amount of cash BWE must provide before Maromba begins producing. That is a real advantage because the period between heavy development spending and first production can be particularly dangerous for a mid cap. It does not, however, transfer Maromba’s underlying economic risk to the financiers. If wells disappoint, production builds more slowly than expected, the FPSO is delayed or oil prices weaken, BWE receives less cash while its financial obligations remain.
The financing has therefore changed the timing and shape of the risk rather than making it disappear. It gives BWE more room during construction and may be exactly the right way to finance a project of this size. The analyst exchange on a possible delay shows the limit: six months can be absorbed comfortably according to management, but a longer delay begins to tighten the position. The arrangements are impressive precisely because Maromba creates such a large funding challenge for a company of BWE’s size.
How much Maromba risk does BWE really need to own?
BWE has already demonstrated that it can create value without accepting this degree of concentrated exposure. Dussafu has worked, Golfinho has added production and created further opportunities in Brazil, and developments around existing infrastructure can require less capital and return cash more quickly. BWE has also sanctioned further investment at Golfinho with management estimating an internal rate of return above 50 per cent at $60 oil, while Bourdon in Gabon is expected to generate a return above 25 per cent with a much smaller cash requirement before first oil.
Those projects are not directly interchangeable with Maromba and their absolute value is smaller, but they demonstrate that BWE has other places to deploy money. Its strengths appear to lie in taking known resources, applying offshore operating expertise, repurposing infrastructure and finding financing structures that improve the economics. Maromba may become the greatest expression of that model, but its scale means that financial, execution and reservoir outcomes are now concentrated in one development expected to produce roughly twice the company’s entire 2025 output.
A return above 30 per cent at $60 Brent is attractive, but the percentage alone cannot answer the shareholder question. Returns have to be considered alongside the capital required to earn them, how long that capital remains at risk, the execution and subsurface assumptions behind the forecast, the consequences of a delay and the opportunities that cannot be pursued with the same financial capacity. Several smaller developments with quicker payback and less concentrated exposure can sometimes produce a better equity outcome than maximising ownership of one enormous project.
This does not mean BWE should abandon Maromba. The project is sanctioned, contracts have been signed and substantial capital has already been committed. The decision today is different from the one management faced before final investment decision. Retaining almost all of Maromba throughout development is nevertheless not the only possible outcome.
As construction progresses and risk falls, BWE may eventually have an opportunity to bring in another equity owner. A farm down could transfer part of the remaining capital requirement together with part of the reservoir, development and commodity exposure while allowing BWE to remain operator and retain substantial participation in the upside. Successful progress on the FPSO, platform and drilling preparations could also make an interest in Maromba more valuable to a potential partner than it was before sanction.
That would leave BWE choosing between maximising its ownership of one transformational project and preserving financial capacity while sharing some of the consequences if Maromba performs differently from plan. Management has a reasonable case that the reservoir is well understood, the economics are attractive and execution remains on schedule and within budget. The equity question is not whether those claims are wrong. It is whether shareholders need BWE to retain almost all of the exposure in order to benefit from success.
BWE has built a good business. Dussafu demonstrated genuine upstream capability, Golfinho broadened the portfolio and the company now generates meaningful cash while enjoying access to financing relationships that many E&Ps would struggle to reproduce. The market is not treating Maromba as an impending crisis, nor should it. Management has addressed the obvious questions about geology, execution and liquidity with credible answers.
Those answers do not remove the concentration question. Good financing can reduce the liquidity risk without transferring the underlying development and reservoir risk away from the equity. If Maromba reaches 60,000 barrels a day broadly on schedule and performs as expected, retaining a large interest may look entirely justified and the value creation could be substantial. If development continues to progress successfully, however, BWE may eventually have the opportunity to crystallise some of that value, share the remaining risk and free capital for the next generation of projects. The strongest evidence of financial discipline may not be proving that it can finance and retain every last part of Maromba itself, but recognising when shareholders would be better served by owning a less of it.